Business
LiteBlue USPS Employee Portal: Login, Security, Payroll and Account Help

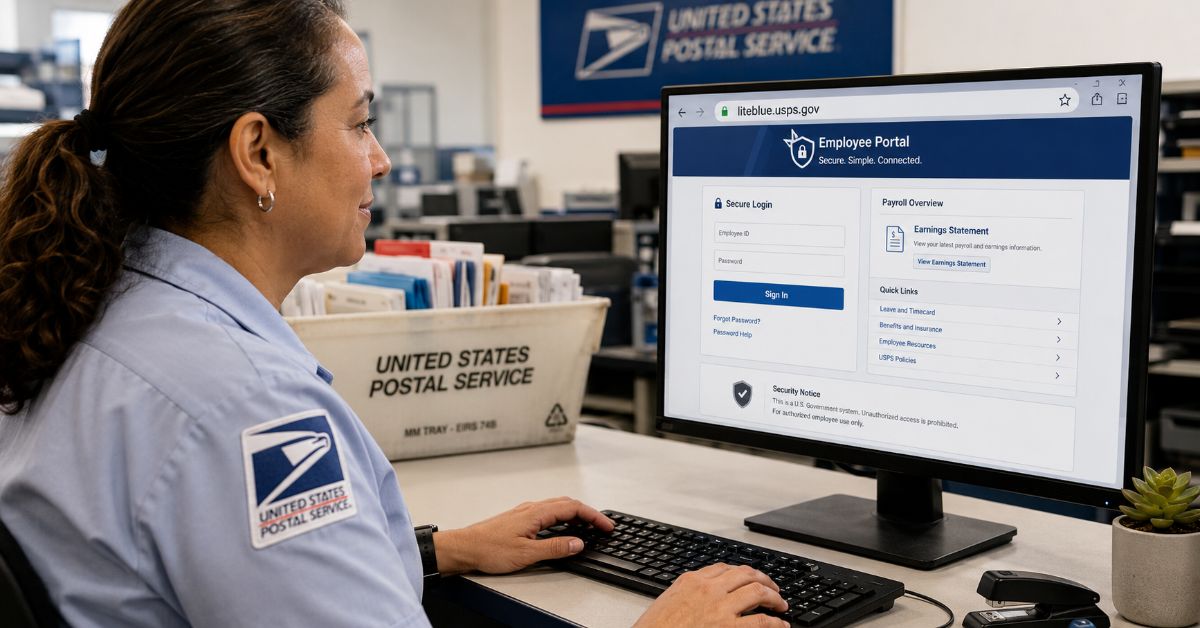
A payroll question can turn into a security problem in seconds if the first link you click is not the real one. That is why the safest way to use LiteBlue starts before you enter a password: check the address bar and make sure you are on liteblue.usps.gov. I treat that domain check as the first step of every LiteBlue task, whether the goal is reviewing earnings, checking benefits information, opening a work-related application, or updating an employee profile.
LiteBlue is the official USPS employee portal, and postal employees use it to reach payroll and benefits information, work-related applications, employee updates, and profile tools. Access typically depends on three things: a USPS Employee Identification Number, often called an EIN, a USPS Self-Service Profile password, and multifactor authentication when USPS requires or enables it for the account. The exact screen flow can change, so the most reliable approach is to begin at the official portal rather than following a reset, payroll, or sign-in link from an email, text message, advertisement, or search result.
This guide is written for USPS employees who want a safe, practical path through the most common LiteBlue questions: what the portal does, what an EIN is, how password recovery should be approached, how multifactor authentication fits into sign-in security, where ePayroll and earnings statements belong in the workflow, and what to do when a website looks suspicious. The central rule is simple: use only liteblue.usps.gov as your starting point. If a page asking for USPS credentials is hosted somewhere else, do not enter them.
What is LiteBlue and what is the official login website?
LiteBlue is the official USPS employee portal. The legitimate website is liteblue.usps.gov. Postal employees use the portal to view payroll and benefits information, reach work-related applications, review employee updates, and manage parts of their employee profile.
For most readers, the search intent behind “LiteBlue” is partly navigational and partly informational. They want to reach the correct USPS employee portal, but they also need to know what credentials are required and how to avoid fake sign-in pages.
A concise answer is: go directly to liteblue.usps.gov, confirm the domain before entering credentials, then sign in using the USPS credentials and security steps required for your account. Do not use a lookalike domain for payroll, benefits, password recovery, or employee profile access.
The table below separates the legitimate access point from common risk signals.
| Check | What to look for | Safe action |
| Website domain | liteblue.usps.gov | Continue only after confirming the domain |
| Login credentials | USPS EIN and Self-Service Profile password | Enter them only on the official portal |
| Extra verification | Multifactor authentication when enabled or required | Complete the prompt through the official sign-in flow |
| Unexpected link | A different domain in email, text, ad, or search result | Do not enter credentials |
| Urgent security message | Pressure to “verify now” on another site | Close it and start again from liteblue.usps.gov |
What do I need to sign in to LiteBlue?
The basic LiteBlue sign-in setup is built around identity, password protection, and, where required, a second verification step. An employee should be prepared with the following:
1. USPS Employee Identification Number, or EIN.
2. USPS Self-Service Profile password.
3. Multifactor authentication access if the account requires it.
These items serve different purposes. The EIN identifies the employee account. The Self-Service Profile password protects access to that account. Multifactor authentication adds another layer by requiring a second verification step beyond the password when it is enabled or required.
What is a USPS Employee Identification Number or EIN?
A USPS Employee Identification Number is the employee identifier used as part of access to USPS employee services such as LiteBlue. In the context of LiteBlue sign-in, the EIN is the identifying credential that works together with the employee’s Self-Service Profile password.
It is important not to treat the EIN as a substitute for a password. An identification number tells the system which employee account is being accessed; the password and any required multifactor step help verify that the person attempting access is authorized.
If you are unsure of your EIN, use trusted USPS employment records or internal USPS resources available to you rather than sending the number through an unverified website or replying to a suspicious message that asks for it.
Why does LiteBlue use a Self-Service Profile password?
The Self-Service Profile password is the password associated with the employee’s USPS self-service access. It is part of the sign-in process for LiteBlue and should be treated as a sensitive credential.
Because LiteBlue can provide access to payroll, benefits, work applications, updates, and profile information, password handling matters. A page that asks for an EIN and password can look convincing even when it is fraudulent. The domain check should therefore happen before the password is typed, not after.
How do I reset my LiteBlue password or get a new one?
Start password recovery from the official LiteBlue website at liteblue.usps.gov. Do not use a password reset link hosted on another domain, even if the message claims to be from USPS or says your account will be locked.
The source information for this guide confirms that LiteBlue uses a USPS Self-Service Profile password but does not provide a fixed sequence of recovery buttons or an alternate reset URL. That distinction matters. Publishing an unverified menu path creates a security problem if USPS changes the sign-in experience.
A safer recovery process is:
1. Type or open liteblue.usps.gov directly.
2. Confirm the domain before interacting with the sign-in page.
3. Use the password recovery or account help option presented within the official USPS flow.
4. Complete any identity or multifactor verification that the official process requires.
5. Create or receive a new password only through the USPS-controlled process.
6. Return to liteblue.usps.gov to sign in again.
If an email or text tells you to “reset LiteBlue now,” do not judge the message by its logo, colors, or wording. Judge it by where the link actually goes. The official domain is the stronger security signal.
This table can help you choose the right response to a password problem.
| Situation | Best next step | What to avoid |
| You forgot the Self-Service Profile password | Start at liteblue.usps.gov and use official account recovery | Third-party “LiteBlue reset” pages |
| A message says your password expired | Open the official portal separately and check there | Clicking the message link automatically |
| A page asks for EIN and password on another domain | Leave the page | Entering credentials to “see if it works” |
| Recovery asks for extra verification | Complete it only inside the official USPS flow | Sharing codes with another person or site |
How do I set up multifactor authentication on LiteBlue?
Multifactor authentication, often shortened to MFA, adds a second verification requirement to the normal sign-in process. On LiteBlue, employees may need MFA when it is enabled for their account or required by USPS.
To set it up safely, begin at liteblue.usps.gov and follow the security or authentication prompts presented by the official USPS sign-in or profile process. The details supplied for this article do not specify one permanent MFA method, screen name, or enrollment path, so it is better to follow the current portal prompts than rely on an old walkthrough.
What should I expect during LiteBlue MFA setup?
The exact interface may change, but the security principle stays the same: MFA should be enrolled through the official USPS environment, not through a third-party site. If setup is required, the authenticated portal should guide you through the verification steps available for your account.
Before completing an MFA prompt, confirm that you reached it from the legitimate LiteBlue domain. If a separate website asks you to “activate USPS MFA” after collecting your EIN and password, that is a reason to stop.
Why does MFA matter for LiteBlue?
LiteBlue is more than an employee news page. It can expose access to payroll and benefits information, work applications, updates, and profile data. A password alone can be compromised through phishing. MFA creates an additional barrier because possession of the password may not be enough to complete sign-in.
That does not make phishing impossible. A fake site may also ask for a verification code. The safest habit is therefore to combine MFA with domain verification. Confirm liteblue.usps.gov first, then complete authentication.
How can I view ePayroll and earnings statements on LiteBlue?
LiteBlue provides access to payroll information, including the employee payroll area commonly associated with ePayroll and earnings statements. Begin by signing in through liteblue.usps.gov using the credentials and authentication required for your account.
After authentication, use the payroll-related tools or work applications made available inside the portal to reach earnings information. Because portal navigation can change, this article does not invent a fixed menu label or number of clicks. The important distinction is that payroll access begins inside the authenticated LiteBlue environment.
A practical payroll workflow looks like this:
1. Open liteblue.usps.gov directly.
2. Verify the domain.
3. Sign in with your EIN and Self-Service Profile password.
4. Complete multifactor authentication if required.
5. Open the payroll or ePayroll function available to your account.
6. Select the earnings statement or payroll information you need.
7. Sign out when finished, especially on a shared or non-personal device.
What information should I verify on an earnings statement?
When reviewing an earnings statement, focus on whether the information matches the pay period and employment context you intended to review. If something appears unfamiliar or inconsistent, do not use an outside website to “correct” payroll information. Return to official USPS resources and follow the support path available through your workplace or authenticated employee systems.
The goal is to keep the entire payroll task within trusted USPS channels. Payroll-related phishing is especially risky because a fraudulent page can use the promise of an earnings statement, direct deposit update, or urgent payroll correction to persuade an employee to enter credentials.
What should I do if I encounter a fake LiteBlue website?
Do not enter your EIN, Self-Service Profile password, or multifactor authentication information on the suspicious site. Close the page and navigate separately to liteblue.usps.gov.
USPS specifically warns employees to use only the official LiteBlue domain. That warning gives employees a clear test: the site may look polished, use postal branding, or copy familiar wording, but if the sign-in page is not on liteblue.usps.gov, it is not the official LiteBlue portal described here.
How can I recognize a LiteBlue lookalike?
A lookalike site tries to make a user focus on appearance instead of origin. The most useful check is the domain.
Watch for these warning signs:
- The address is similar to “liteblue” but is not liteblue.usps.gov.
- The page arrived through an unsolicited email, text, ad, or unexpected message.
- The site creates urgency around payroll, benefits, password expiration, or account suspension.
- The page asks for the same credentials as LiteBlue but is hosted outside the official domain.
- The site asks for multifactor information after leading you through a non-USPS sign-in page.
A familiar logo is not proof of legitimacy. The domain is more useful than visual design because images and page layouts can be copied.
What if I already entered my LiteBlue credentials on a suspicious site?
Stop using the suspicious site and return directly to liteblue.usps.gov. Use the official account security or password recovery process available through USPS to secure access, and follow any internal USPS security reporting process available to you.
Do not continue interacting with the fake site to “undo” the submission. Do not send additional verification information. The priority is to re-establish control through the official USPS environment.
How do LiteBlue login, payroll, password recovery, and security fit together?
The most useful way to think about LiteBlue is as one trusted entry point for several employee tasks. Instead of searching separately for “LiteBlue payroll,” “LiteBlue password reset,” or “LiteBlue MFA,” start from the same verified domain and then move to the appropriate function.
The table below summarizes that trust-first workflow.
| Your goal | Start here | Credential or security need | Key safety rule |
| Sign in to LiteBlue | liteblue.usps.gov | EIN, Self-Service Profile password, MFA if required | Check the domain first |
| Review payroll or earnings | Official LiteBlue portal | Authenticated employee access | Reach payroll from inside LiteBlue |
| Reset a password | Official LiteBlue portal | Official recovery and identity checks | Avoid external reset links |
| Set up or complete MFA | Official USPS sign-in/profile flow | Second-factor verification | Enroll only through USPS-controlled pages |
| Review benefits or profile information | Official LiteBlue portal | Authenticated employee access | Do not share credentials |
| Respond to a suspicious site | Close it and return to official LiteBlue | Account recovery if needed | Never trust lookalike domains |
This approach reduces a common security mistake: treating every employee task as a separate web search. The more often an employee searches for a specialized login or reset page, the more chances there are to land on a misleading result. A bookmarked official domain can reduce that exposure.
What is the safest routine for using LiteBlue?
A short routine is easier to remember than a long list of security rules. Before every LiteBlue session, check the domain, then authenticate, then open the tool you need.
Use this sequence:
1. Start from liteblue.usps.gov.
2. Confirm the spelling and domain before entering credentials.
3. Enter your EIN and Self-Service Profile password only on the official site.
4. Complete MFA if required.
5. Use payroll, benefits, work applications, updates, or profile tools from within the authenticated portal.
6. Sign out when the session is complete.
I would also avoid saving or sharing screenshots that expose an EIN, authentication prompt, payroll details, or other employee information. The original LiteBlue details emphasize phishing and lookalike websites, and the safest interpretation is to keep credentials and employee data inside the legitimate USPS environment whenever possible.
Conclusion: make the official domain your first security check
The most important LiteBlue habit is also the simplest: begin at liteblue.usps.gov and verify the address before entering anything sensitive. Your EIN identifies the employee account, your Self-Service Profile password protects access, and multifactor authentication can add another verification layer when USPS requires it.
Once authenticated, LiteBlue serves as the gateway to payroll and benefits information, work-related applications, employee updates, and profile tools. For password recovery, MFA, and payroll access, avoid relying on third-party walkthroughs that may become outdated or lead to lookalike pages. A trust-first workflow is safer: official domain first, authentication second, employee task third.
Frequently Asked Questions
Can I use a website other than liteblue.usps.gov to sign in to LiteBlue?
No. The legitimate LiteBlue website identified in the provided USPS information is liteblue.usps.gov. If another site asks for your USPS EIN, Self-Service Profile password, or authentication information, do not enter it.
Is my USPS EIN the same thing as my LiteBlue password?
No. The EIN identifies the employee account, while the Self-Service Profile password is the password used to protect access. They serve different roles in the sign-in process.
Do all LiteBlue users need multifactor authentication every time?
The supplied information states that multifactor authentication may be enabled or required. Follow the current authentication prompts presented through the official USPS LiteBlue sign-in flow for your account.
Can I reset my LiteBlue password from a link in an email?
The safer approach is to open liteblue.usps.gov directly and start recovery there. This avoids trusting a link that could point to a lookalike or phishing website.
Where should I start if I only want to check my earnings statement?
Start at liteblue.usps.gov, sign in with the required credentials, complete MFA if required, and then use the payroll or ePayroll function available inside the authenticated employee portal.
What is the quickest way to check whether a LiteBlue page is legitimate?
Look at the domain before entering credentials. The official website is liteblue.usps.gov, so a similar-looking address on another domain should not be treated as the official LiteBlue portal.
Real Estate Investing in 2026 is not a shortcut to passive income; with the average U.S. 30-year fixed mortgage at 7.28% on October 1, a deal that survives only on optimistic rent, low repairs, or future appreciation is already fragile. The better question is not “Which property should I buy?” but “What combination of income, debt, operations, reserves, and exit options can I defend with evidence?”
That shift matters because “real estate” covers investments that behave very differently. A publicly traded REIT can be bought or sold through a brokerage account. A single-family rental can concentrate income in one tenant and force the owner to absorb every roof, HVAC, vacancy, and insurance surprise. A private property deal can look passive while locking capital away for years. Land may have low day-to-day operating work but no cash flow and a future value that depends on approvals that may never arrive.
Readers who first need a broader way to match any investment to goals, time horizon, liquidity, and risk capacity can use Aperplexity’s investment strategy framework as the portfolio-level starting point. This guide goes one level deeper: it treats property as a small operating business and shows how to pressure-test the numbers before capital is trapped in an illiquid asset.
The goal is not to produce one “best” strategy. It is to create a repeatable decision system: choose the ownership form that fits the investor, underwrite the economics, audit the assumptions, stress-test the downside, and verify the legal and physical facts before closing.
1. Start With the Investor, Not the Property
A property can be objectively attractive and still be wrong for a specific investor. Before looking at listings, define five constraints: available capital, borrowing capacity, time available for management, required liquidity, and the amount of leverage or loss the investor can tolerate. These constraints eliminate bad fits faster than scrolling through deals.
| Investor situation | Strategies worth researching | Main risk to test |
| Limited capital; willing to live on-site | House hacking; owner-occupied small multifamily | Lifestyle disruption, occupancy rules, repair reserves |
| High income; little free time | Public REITs; professionally managed rentals | Fees, market volatility, weak oversight of managers |
| Construction / project skills | Value-add rentals; renovation; small development | Cost overruns, permits, carrying costs |
| Needs strong liquidity | Publicly traded REITs | Equity-market volatility and sector concentration |
| Long horizon; specialist knowledge | Private deals; land; development | Illiquidity, sponsor risk, uncertain exit |
This immediately exposes a common mistake: treating direct ownership and real estate exposure as the same thing. They are not. Control, liquidity, workload, concentration, tax treatment, and leverage can differ sharply.
2. Direct Ownership, REITs, and Private Deals Solve Different Problems
Publicly traded REITs provide real-estate exposure without direct property management and are generally easier to trade than physical property. Investor.gov notes that REITs own or operate income-producing real estate or related assets, while publicly traded REIT shares can typically be bought and sold on an exchange. That liquidity is a feature, but it also means prices can move with public markets rather than only with appraised property values.
| Route | Control | Liquidity | Operational work | Primary failure mode |
| Direct rental | High | Low | High unless outsourced | Vacancy, repairs, financing, local regulation |
| House hacking | Medium-high | Low | Medium-high | Lifestyle conflict and under-budgeted ownership costs |
| Public REIT | Low | High | Low | Market drawdowns, sector exposure, management decisions |
| Private/crowdfunded deal | Low-medium | Low | Low day-to-day | Sponsor risk, fees, lockups, opaque valuation |
| Land | High | Low | Low-medium | Carrying costs and a future use that never materializes |
The category label matters less than the constraint it solves. REITs can solve a liquidity and workload problem. Direct ownership can solve a control problem. A private deal may provide access to larger assets but replaces landlord work with sponsor due diligence and lockup risk.
3. Underwrite a Rental From Effective Income Down
A rental should be analyzed from effective income downward, not from “rent minus mortgage.” Potential gross rent is only the starting point. Adjust it for vacancy and collection loss, then add realistic ancillary income such as parking, storage, laundry, or utility reimbursements when those amounts are documented.
Effective Gross Income = Potential Gross Income − Vacancy Loss − Collection Loss + Other Income
The national rental vacancy rate was 7.3% in the second quarter of 2026, according to the U.S. Census Bureau. That is not a plug-in assumption for every market; it is evidence that vacancy is real and measurable. A local underwriting model should use local rent comps, lease history, turnover, property quality, and competing supply rather than choosing a convenient round number.
For an investor analyzing apartments, it also helps to understand the renter’s side of the transaction. Aperplexity’s apartment-renting guide breaks sticker rent into effective rent, recurring fees, cash-to-keys, and exit exposure—useful clues for judging what tenants actually compare when deciding whether a unit is rentable.
Operating expenses are broader than taxes and insurance
Include property taxes, insurance, repairs, routine maintenance, property management, owner-paid utilities, landscaping, pest control, legal/accounting costs, licenses, inspections, HOA charges, and reserves for major replacements. If the owner performs management personally, the model should still include a market-based management cost; otherwise unpaid labor is being mislabeled as investment return.
Separate repairs from capital replacements
A leaky faucet and a new roof are not the same economic event. Routine repairs belong in ongoing operating costs. Roofs, HVAC systems, parking surfaces, major plumbing, and other replacements create lumpy capital needs. A property can show positive monthly cash flow while silently accumulating “deferred maintenance debt.”
4. Know What NOI, Cash Flow, Cap Rate, and Cash-on-Cash Return Actually Measure
Net operating income (NOI) is effective gross income minus operating expenses. It generally excludes mortgage principal and interest, income taxes, depreciation, and owner-specific financing costs. Because sellers and brokers may classify expenses differently, the calculation should be rebuilt from source documents rather than accepted as a label.
NOI = Effective Gross Income − Operating Expenses
Cap rate compares NOI with property value or purchase price. Cash-on-cash return compares pre-tax cash flow with the actual cash invested. The two can move in different directions because leverage affects cash-on-cash return but not property-level NOI.
Cash-on-Cash Return = Annual Pre-Tax Cash Flow ÷ Total Cash Invested
Total cash invested should include the down payment, closing costs, inspections, immediate repairs, furnishing when relevant, permits, loan fees, utility deposits, and initial reserves. A high cash-on-cash return created by aggressive leverage is not automatically a better risk-adjusted deal.
5. Debt Is a Return Multiplier and a Failure Multiplier
Debt can increase equity returns when the property performs, but it also narrows the margin for error. Important financing inputs include the rate, term, amortization period, down payment, closing costs, points and fees, prepayment penalties, balloon or maturity risk, variable-rate exposure, and lender debt-service coverage requirements.
DSCR = NOI ÷ Annual Debt Service
A higher debt-service coverage ratio generally provides more room for vacancy or expense shocks, but there is no universal “safe” figure because lenders define NOI differently and property risk varies. The useful discipline is to calculate DSCR using both the lender’s definition and a conservative owner-underwriting definition.
6. Use an Assumption Audit Before Believing the Spreadsheet
Most bad deals do not begin with a broken formula. They begin with a clean spreadsheet built on weak assumptions. For every input that materially changes the result, record the assumption, its source, the date, whether it is verified or estimated, and what happens if it is wrong.
| Assumption | Evidence to collect | Downside test |
| Rent | Executed leases, recent comparable leases, listing concessions | 5–10% lower achievable rent |
| Vacancy | Local data, building history, competing supply | Longer lease-up + one unexpected turnover |
| Insurance | Property-specific quote and exclusions | 20–40% higher premium or higher deductible |
| Repairs / capex | Inspection + contractor estimates | One major replacement in first 24 months |
| Taxes | Current bill + reassessment rules | Post-sale reassessment or use change |
| Exit value | Comparable sales and buyer pool | Lower price + longer selling period |
The same discipline used in an auditable business model applies here: inputs should be separated from outputs, downside scenarios should be editable, and cash consequences should be visible. Aperplexity’s discussion of financial-model structure is aimed at startups, but the modeling principle transfers cleanly to property underwriting.
7. Four Risks Beginner Guides Underweight
The rentability gap
A unit can be legally rentable yet economically difficult to rent at the headline comparable rate. Layout, parking, laundry, noise, natural light, cooling, internet quality, pet rules, safety perception, and nearby supply can create a gap between “market rent” and the rent this exact unit can sustain.
The management-friction score
Two properties can show identical projected returns while demanding very different amounts of work. Score unit count, age of major systems, turnover, owner distance, utility complexity, maintenance-call frequency, vendor availability, and tenant communication demands. The score is not a universal metric; it is a way to price operational burden instead of calling every rental “passive.”
The insurance-availability test
Insurance is not just a percentage line item. Obtain a realistic quote before finalizing the offer and ask about deductibles, roof or system exclusions, replacement-cost coverage, flood/wildfire/hurricane exposure, loss-of-rent coverage, and whether multiple carriers will insure the property. A deal that works only with an outdated premium estimate is not underwritten.
The exit-liquidity test
Do not ask only “Can I afford to buy this?” Ask “Who can buy this from me later, with what financing, and how long could that take?” Evaluate the likely buyer pool, property condition, zoning, insurance costs, local transaction volume, tenant lease terms, major employers, and selling costs. Narrow buyer pools create price risk even when current cash flow looks acceptable.
Boundary and parcel wording deserves the same caution. Terms such as “adjacent,” “adjoining,” and “contiguous” can carry different meanings depending on the legal instrument and jurisdiction; Aperplexity’s property-language explainer is a useful reminder not to turn casual listing language into a legal conclusion.
8. Worked Example: A Deal That Looks Fine Until It Is Stressed
Consider a fictional $320,000 rental. The investor puts 25% down, contributes $8,000 in closing and loan costs, spends $12,000 on initial repairs, and keeps a $10,000 operating reserve. The property is expected to rent for $2,800 per month with $100 of other monthly income. These figures are illustrative—not market guidance.
| Variable | Base case | Downside case |
| Potential monthly rent | $2,800 | $2,600 |
| Vacancy / collection loss | 5% | 10% |
| Other monthly income | $100 | $75 |
| Annual operating expenses | $11,800 | $14,500 |
| Annual capital reserve | $3,000 | $4,500 |
| Annual debt service | $18,600 | $20,400 |
| Selling period if exited | 5 months | 12 months |
Base case effective income is approximately $33,020 per year: $33,600 potential rent less 5% vacancy ($1,680) plus $1,200 other income. After $11,800 of operating expenses, NOI is about $21,220. Subtract $18,600 of debt service and a $3,000 capital reserve and the property produces roughly negative $380 of pre-tax cash flow.
That result is the point. A property can look acceptable when someone quotes gross rent, a cap rate, or “tenant pays the mortgage,” yet still fail after vacancy, real expenses, reserves, and financing are included. In the downside case, lower rent, higher vacancy, higher operating costs, a larger capital reserve, and more debt service deepen the loss. Appreciation could still create a positive long-term outcome, but it should not be used to disguise weak operating economics.
9. Due Diligence Is Where the Spreadsheet Meets Reality
Underwriting should create a list of facts that must be verified before the deal becomes hard to unwind. Organize diligence into four files: financial, physical, legal/regulatory, and market.
- Financial: leases, rent roll, bank deposits, historical income and expenses, utility bills, tax records, insurance quotes, debt or liens, and seller concessions.
- Physical: roof, structure, drainage, electrical, plumbing, HVAC, windows, insulation, moisture, pests, sewer/septic, parking, access, and safety equipment.
- Legal/regulatory: zoning, permitted use, rental licenses, open violations, occupancy limits, building permits, HOA rules, lease restrictions, and local short-term-rental rules where relevant.
- Market: comparable rents and sales, new supply, vacancy, major employers, transportation, neighborhood factors, climate exposure, and planned infrastructure.
IRS Publication 527 is also a reminder that tax accounting is not the same as cash accounting. Residential rental owners may report rental income and deduct eligible expenses, while depreciation follows specific basis, recovery-period, and placed-in-service rules. Tax treatment can materially affect after-tax returns, so property-specific tax questions belong with a qualified professional rather than a generic return calculator.
10. Common Real Estate Investing Mistakes That Survive Good Markets
- Using appreciation to rescue negative operating cash flow. Future price gains are uncertain and may not arrive when the investor needs to sell.
- Ignoring the cost of owner labor. Self-management is work; excluding a management cost inflates the economic return.
- Assuming the seller’s tax bill, insurance premium, or maintenance history will continue unchanged after the purchase.
- Confusing gross rent with reliable income. Vacancy, nonpayment, concessions, turnover, and repairs reduce what is actually collected.
- Underestimating transaction costs on both entry and exit, including commissions, title, legal, financing, repairs, and concessions.
- Buying a property that fails under ordinary surprises. One vacancy, one major repair, or one financing change should not destroy the plan.
11. A Six-Dimension Readiness Test
Before committing, score the opportunity on six dimensions. The purpose is not to create a fake precision score. It is to force a complete conversation before the investor falls in love with the property.
| Dimension | Question to answer |
| Income quality | Is the income documented, achievable, and resilient to normal vacancy? |
| Expense visibility | Are operating costs and capital replacements known rather than guessed? |
| Debt resilience | Can the property survive weaker rent, repairs, and financing stress? |
| Operational simplicity | Can it be managed reliably without excessive unpaid owner labor? |
| Exit liquidity | Is there a credible future buyer or refinancing pool? |
| Regulatory durability | Is the intended use likely to remain legally and practically usable? |
The Future of Real Estate Investing in 2027
The strongest 2027 signal is not a universal price forecast. It is that financing, insurance, and local supply will keep separating strong properties from weak ones. Mortgage costs were elevated in early October 2026, and that makes refinancing assumptions and debt maturity risk more important. A rate decline would help some deals, but underwriting should not require it.
Rental conditions are also local. The U.S. rental vacancy rate was 7.3% in the second quarter of 2026, but metro-level conditions can diverge sharply. Investors should expect concessions, new construction, employer changes, and household formation to affect achievable rent more than national averages alone.
Technology will continue making data, remote management, fractional access, and private-deal discovery easier. That improves access to information; it does not remove property-level risk. The likely advantage in 2027 is not faster deal discovery. It is better verification: current insurance quotes, local rent evidence, document-level diligence, and downside scenarios that are updated when facts change.
Takeaways
- Real estate is an operating asset before it is a wealth-building story; underwrite income, expenses, reserves, and debt in that order.
- Choose the ownership route after defining capital, leverage, time, liquidity, and risk constraints.
- Rebuild NOI from source documents and keep financing separate from property-level operating performance.
- Treat insurance availability, management workload, tenant concentration, and exit liquidity as core underwriting—not footnotes.
- Use downside cases that combine several realistic problems at once; one-variable stress tests are too forgiving.
- Verify legal, physical, tax, and market facts before closing because a spreadsheet cannot repair a bad title, failing roof, or prohibited use.
- Prefer deals that remain defensible when assumptions worsen, rather than deals that need appreciation or refinancing to become acceptable.
Conclusion
The durable way to approach real estate investing is to stop treating the purchase as the finish line. The real decision is whether the asset can produce credible income, absorb ordinary expenses, carry its debt, survive operational friction, and eventually be sold or refinanced without forcing the investor into a bad outcome.
That standard is stricter than a beginner checklist, and it should be. Physical property is illiquid, transaction-heavy, locally regulated, and expensive to fix after the fact. REITs and private vehicles remove some ownership burdens but introduce different risks around market pricing, fees, sponsors, and control.
A good investment does not need perfect forecasts. It needs assumptions that can be explained, evidence that can be checked, reserves that can absorb surprises, and an exit that still exists when conditions are less favorable than expected. That is a more useful definition of “good real estate” than a hot market, a low purchase price, or a headline yield.
Frequently Asked Questions
What is real estate investing?
Real estate investing means committing money to property or real-estate-related securities with the goal of earning income, appreciation, tax benefits, or a combination. It can include direct rentals, house hacking, land, private property deals, and REITs. These routes differ substantially in control, liquidity, workload, leverage, and risk.
How much money do you need to start real estate investing?
There is no universal minimum. Publicly traded REITs can be accessed with far less capital than a directly owned rental, while direct ownership typically requires a down payment plus closing costs, repairs, reserves, and financing capacity. The correct starting point is the investor’s liquidity and risk constraints, not a promotional minimum.
How do you analyze a rental property before buying?
Estimate effective rental income, subtract realistic operating expenses to calculate NOI, model financing separately, fund a capital reserve, then calculate pre-tax cash flow and cash-on-cash return. Verify rent, taxes, insurance, repairs, legal use, and local market assumptions before relying on the result.
What is the difference between cap rate and cash-on-cash return?
Cap rate compares property-level NOI with the property’s price or value and ignores the investor’s financing. Cash-on-cash return compares annual pre-tax cash flow with the actual cash invested. Leverage can therefore change cash-on-cash return without changing the property’s NOI.
Are REITs safer than rental properties?
Not automatically. Public REITs usually offer better liquidity and diversification than owning one property, but their market prices can be volatile and investors have less control over assets and management. A rental concentrates property and tenant risk but gives the owner more direct control. “Safer” depends on the risk being measured.
What hidden costs should a rental-property investor budget for?
Beyond the mortgage, budget for vacancy, repairs, property management, utilities paid by the owner, insurance, taxes, legal/accounting work, licenses, HOA charges, turnover, and capital replacements such as roofs or HVAC systems. Buying and selling costs should also be included in the full return analysis.
What is the biggest mistake new real estate investors make?
The most damaging pattern is underwriting a deal that only works under favorable assumptions. If the property needs full occupancy, low repairs, cheap insurance, stable taxes, rising prices, and easy refinancing at the same time, the apparent return is compensation for fragility rather than proof of a strong investment.
Methodology
Research was conducted on October 6, 2026. A current high-visibility competitive sample for the focus query and close variants was reviewed, including InvestmentKit, REICommunity, RealEstate101, Facet, Rentometer, Rent To Retirement, BiggerPockets, InvestmentKit’s REIT/direct-property comparison, WealthVieu, and Fourmio. Search order varies by location, device, personalization, and index freshness, so this is a competitive benchmark rather than a permanent global top ten.
The recurring SERP strength was broad beginner coverage: definitions, investment types, financing, rental basics, and lists of strategies. The recurring gap was deal resilience. This article was therefore structured independently around investor constraints, effective-income underwriting, assumption auditing, operating friction, insurance availability, downside combinations, and exit liquidity rather than mirroring any competitor’s section order.
Primary validation prioritized Freddie Mac for current mortgage rates, the U.S. Census Bureau for rental vacancy, IRS Publication 527 for residential rental tax mechanics, and Investor.gov for REIT structure and liquidity context. Internal links were verified as live on aperplexity.com on the research date. The worked property is fictional and is designed to demonstrate method, not expected returns. Local rents, taxes, insurance, financing, zoning, and transaction costs must be replaced with current property-specific evidence.
This article was drafted with AI assistance and reviewed by a human editor before publishing. All data, citations, and claims have been independently verified against primary sources.
References
- Freddie Mac. (2026, October 1). Mortgage rates average 7.28%.
- Internal Revenue Service. (2026). Publication 527 (2025), Residential Rental Property.
- U.S. Census Bureau. (2026, July 28). Quarterly Residential Vacancies and Homeownership, Second Quarter 2026.
- U.S. Securities and Exchange Commission, Office of Investor Education and Advocacy. (n.d.). Real Estate Investment Trusts (REITs). Investor.gov.
- U.S. Securities and Exchange Commission, Office of Investor Education and Advocacy. (2016, August 30). Investor Bulletin: Publicly Traded REITs. Investor.gov.
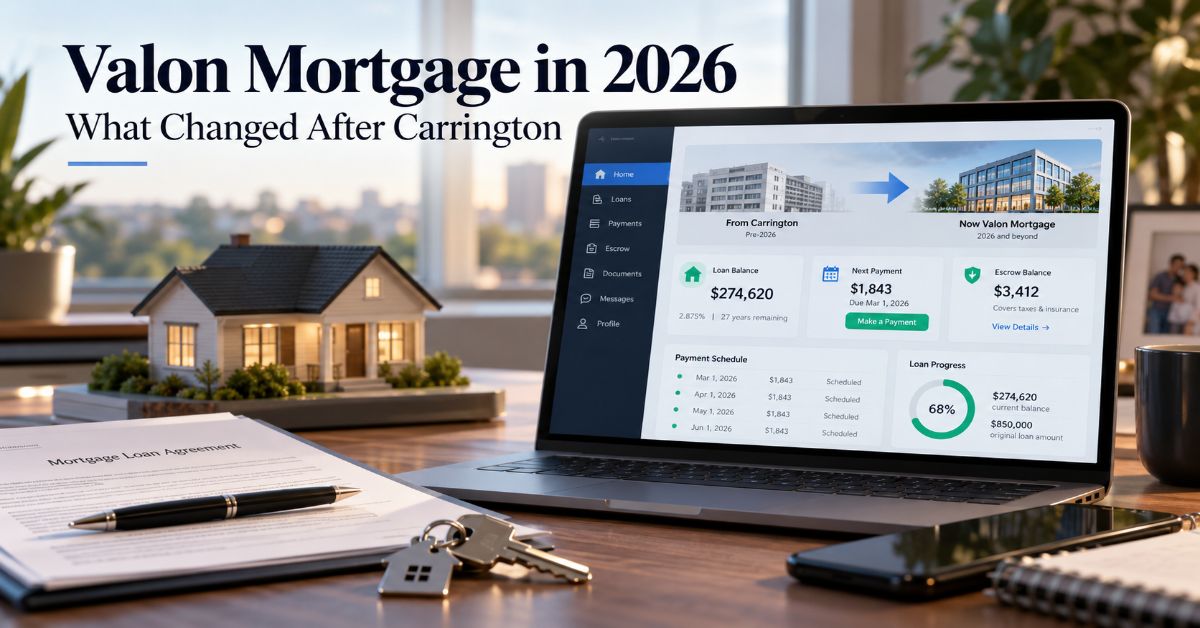
Valon Mortgage is a mortgage lender and servicing business whose real significance comes from doing things in the reverse order of many digital lenders: it built mortgage-servicing infrastructure first, then expanded into consumer lending. That story changed again in 2026, when Carrington Mortgage Services completed its acquisition of Valon Mortgage, while Valon Technologies kept building ValonOS as mortgage-servicing software. HousingWire reported the completed transaction in August 2026.
That makes many older Valon Mortgage reviews incomplete. A borrower searching the name today may be trying to understand a lender, a servicer shown on a mortgage statement, a transferred loan, or the technology company behind the servicing system. Those are related, but they are not the same thing.
This guide separates them. It explains what Valon built, why the company chose a servicing-first strategy, what loan products and geographic limits its borrower-facing pages have listed, what the Carrington transaction changed, how public complaints should be interpreted, and what to check before applying for a mortgage or reacting to a servicing transfer.
What Is Valon Mortgage Now?
The cleanest 2026 answer is that Valon Mortgage was the regulated mortgage operating business built by Valon Technologies, and that business was acquired by Carrington Mortgage Services. Valon Technologies remains the technology company behind ValonOS, the servicing platform that was proven inside Valon’s own operating business before being deployed to larger institutions.
Valon’s current corporate site says the company was built around modern mortgage servicing technology and notes that Valon Mortgage was acquired by Carrington in 2026. The separate Valon technology site describes ValonOS as a unified system of record for regulated mortgage workflows.
| Entity | What it is | Why it matters in 2026 |
| Valon Mortgage | The mortgage lending/servicing operating business acquired by Carrington | Borrowers may still encounter the Valon name in loan history, help content, or servicing transitions. |
| Carrington Mortgage Services | The acquirer of Valon Mortgage | Carrington gained roughly 810,000 loans and planned to run core servicing on ValonOS. |
| Valon Technologies | The technology company | It now centers more clearly on software rather than operating a mortgage servicer itself. |
| ValonOS | Mortgage-servicing system of record and workflow platform | The technology is being adopted by large servicing organizations, including Carrington and Newrez plans. |
Why Valon Built Servicing Before Selling More Loans
Valon’s most distinctive strategic choice was not a flashy consumer app. It was the decision to enter one of the most regulated, operationally messy parts of housing finance—servicing—and operate it at scale before asking major institutions to trust the software.
Mortgage origination is the process of qualifying a borrower and creating a loan. Servicing begins after the loan exists: collecting payments, maintaining escrow, handling tax and insurance disbursements, producing statements and payoff information, supporting hardship cases, applying investor rules, and maintaining a compliance record. A lender can originate a loan and then sell the servicing rights or transfer servicing to another company.
Valon’s thesis was that legacy servicing systems created high operating cost and poor borrower experiences. By becoming a servicer itself, the company could discover the edge cases that a software-only startup might miss. That operational experience became a form of product validation.
This is also why the model is more interesting than a standard lender review. A borrower thinking about how principal and interest actually move through a long-term loan can pair this article with Aperplexity’s amortization schedule guide, which explains how servicing mechanics and payment application can affect the real path of a loan.
The 2026 Acquisition Changes the Story
In May 2026, Carrington and Valon announced a transaction under which Carrington would acquire Valon Mortgage and adopt ValonOS. The deal closed in August. HousingWire reported that the acquisition added about 810,000 loans to Carrington’s servicing portfolio and that ValonOS would become a core technology platform.
For Valon, this was not simply an exit from mortgages. It was evidence that the company’s original long route—build software, operate a servicer, prove the system under regulation, then sell the infrastructure—had reached a new stage. Valon Technologies could focus more directly on software while a larger servicing operator took over the mortgage operating business.
For borrowers, the distinction is practical: brand, loan owner, servicer, technology platform, and customer-support organization can be different entities. A transfer of servicing does not by itself change the underlying mortgage terms, but it can change where payments are sent, which portal is used, and who handles escrow or customer service.
Loan Products Valon Has Offered
Valon’s help center lists standard home-purchase mortgages, refinances, home-equity products, conventional and jumbo loans with fixed or adjustable rates, and FHA loans. It also states that VA and USDA loans are not currently supported. See Valon’s loan-type guidance.
For readers comparing debt choices, the product label is only the beginning. A refinance replaces the existing mortgage, a cash-out refinance increases the new balance to release equity, a HELOC creates a reusable line of credit, and a home equity loan usually provides a lump sum with its own repayment schedule.
| Product | Typical use | Key issue to compare |
| Purchase mortgage | Buying a home | Rate, APR, points, down payment, closing costs, servicing destination |
| Rate/term refinance | Changing rate or term | Break-even period versus closing costs |
| Cash-out refinance | Replacing first mortgage while extracting equity | New first-mortgage rate applied to a larger balance |
| HELOC | Flexible access to home equity | Variable-rate risk, draw period, fees, minimum draws |
| Home equity loan | One-time lump-sum equity borrowing | Fixed payment versus using a line of credit |
| FHA loan | Government-insured borrowing for eligible applicants | Mortgage insurance and total cost |
A homeowner deciding whether extra cash should reduce debt or remain invested also faces a broader capital-allocation question. Aperplexity’s investment strategies guide is useful for separating liquidity, time horizon, risk, and opportunity cost before treating mortgage prepayment as automatically superior.
Where Valon Mortgage Has Operated
Valon’s help center states that standard residential mortgages are offered in all U.S. states except Hawaii, Nevada, New York, and Utah, and are not offered in Puerto Rico, Guam, or the U.S. Virgin Islands. It separately lists home-equity products in 36 states. Because licensing and product coverage can change, borrowers should verify current eligibility before relying on an older review. The official state-availability page should be checked on the day of application.
The distinction between standard mortgages and home-equity products matters. A lender can be licensed to originate one product in a state without offering every product there. Search results that simply say ‘available in 46 states’ can therefore create false confidence if the borrower actually wants a HELOC or home equity loan.
Will Valon Keep Servicing a Loan After Closing?
Historically, Valon said it serviced most loans it originated, but not all of them. Its help center explains that some loans may be transferred because of financing-partner constraints. That caveat is important because one of Valon’s strongest marketing distinctions was the possibility of keeping origination and servicing closer together. The company’s servicing-policy page makes the ‘most, not all’ position explicit.
After the 2026 Carrington transaction, borrowers should be even more precise about what they are asking. ‘Will Valon service my loan?’ may no longer be the right question. Better questions are: Which legal entity is originating this loan? Who is expected to service it at closing? Can servicing be transferred? Which portal and payment address should I use after any transfer?
Rates, Fees, and the Loan Estimate Matter More Than Ads
A mortgage rate is not a single company-wide price. It depends on market conditions and borrower-specific factors such as credit profile, loan-to-value ratio, property type, occupancy, loan amount, product, points, and lock period. That is why a static ‘Valon mortgage rates’ table becomes stale quickly.
The better comparison document is the Loan Estimate. It lets borrowers compare rate, APR, projected payment, lender credits, points, origination charges, prepaids, escrow amounts, and cash to close. Two lenders can advertise similar rates while producing meaningfully different total costs.
Housing decisions also compete with other cash demands. Someone moving, paying a deposit, or rebuilding reserves after closing may benefit from the same all-in-cost discipline used in Aperplexity’s apartment renting guide: compare the headline payment with the real cash required to enter and carry the obligation.
Public Reviews and Complaints: What They Do and Do Not Prove
Public feedback on Valon is mixed. Trustpilot showed a 3.5/5 TrustScore with 260 reviews when checked in 2026, while BBB review pages showed materially lower averages and a separate complaint record. ConsumerAffairs also carried strongly negative borrower reports. These sources are useful for identifying recurring friction, but they are not a controlled measure of the average borrower experience.
The patterns matter more than one dramatic story. Repeated themes in 2026 reviews included escrow and insurance handling, payment posting, transfer confusion, difficulty getting consistent answers, and customer-service delays. Positive reviews often emphasized ease of the online platform, helpful staff, or smooth lending/equity transactions.
A borrower should not infer fraud, illegitimacy, or universal service failure from complaint pages. Review platforms are self-selected and can overrepresent people with strong experiences. But recurring operational complaints are still a reason to verify documents, keep payment records, save transfer notices, and escalate discrepancies quickly.
| Due-diligence check | What to verify | Why it matters |
| Loan terms | Loan Estimate and Closing Disclosure | Protects against comparing only the advertised rate |
| Servicer identity | Current statement, transfer notice, official portal | Prevents payment to the wrong destination |
| Escrow | Taxes, insurance, cushion, disbursement history | Escrow errors can change monthly payments materially |
| Credit pull | Whether the step is quote/prequalification or full application | A full application may involve a hard inquiry |
| State/product availability | Current official eligibility | Coverage can differ between mortgages and HELOC/HELOAN products |
| Complaint pattern | Recent CFPB/BBB/public reviews | Useful as a risk signal, not a verdict |
Valon vs. Rocket, Better, and a Traditional Bank
The most useful comparison is business model, not a generic winner ranking. Rocket built a massive direct-to-consumer origination and servicing brand. Better Mortgage emphasized digital origination and automation. Traditional banks can combine mortgage lending with deposits, branches, and other financial relationships. Valon’s distinctive path was servicing infrastructure first, then lending, then a 2026 separation in which Carrington acquired the operating mortgage business while Valon Technologies pushed the servicing platform.
That difference may matter to borrowers who care about the post-closing experience, but it does not automatically make a loan cheaper. The right lender is the one offering the best combination of total cost, product fit, execution certainty, service quality, and servicing expectations for the specific borrower.
Who Is This Model Best For?
Before the Carrington acquisition, Valon’s borrower-facing model was most compelling for people who wanted a digital process and liked the possibility that the same ecosystem could continue servicing the loan. It could also be relevant for homeowners comparing refinance, HELOC, or home equity options.
It was a weaker fit for borrowers needing VA or USDA programs, people in excluded states, commercial-property borrowers, or anyone who assumed that every Valon-originated loan would remain with the same servicer.
Borrowers using retirement savings or considering a 401(k) loan to fund housing costs should treat that as a separate financial decision. Aperplexity’s Fidelity AARP 401(k) warning guide explains why retirement-plan loans and withdrawals have their own tax, liquidity, and job-separation risks.
The Future of Valon Mortgage in 2027
The 2027 story is likely to be less about Valon as a consumer mortgage brand and more about ValonOS as infrastructure. Rithm Capital announced in February 2026 that Newrez planned to deploy Valon’s technology across more than four million homeowners, and Carrington is adopting ValonOS after acquiring Valon Mortgage.
That direction supports a larger industry trend: servicing technology is moving from old, fragmented cores toward cloud software, integrated workflows, automation, and AI-assisted operations. The hard part is not adding a chatbot. Mortgage servicing has to reconcile money movement, investor rules, escrow, compliance, customer communication, and exceptions without losing an auditable system of record.
The key uncertainty is execution. Large servicing-platform conversions are operationally risky, and Valon’s headline efficiency claims are company-reported rather than independently audited. Adoption by large servicers is meaningful evidence of commercial traction, but borrowers will judge the result through payment accuracy, escrow handling, response times, and transfer quality.
Key Takeaways
- Valon Mortgage should be understood through its servicing-first history, not only as an online lender.
- Carrington completed its acquisition of Valon Mortgage in August 2026; Valon Technologies retained ValonOS and is now more clearly a technology company.
- Official help pages list purchase/refinance mortgages, conventional and jumbo products, FHA loans, HELOCs, and home equity loans, but not VA or USDA loans.
- Mortgage availability and home-equity availability are not identical; verify the exact product in the borrower’s state.
- Servicing can transfer. Confirm who will service the loan, where payments go, and how escrow is handled.
- Public review sites reveal recurring operational risks but should not replace document-level due diligence.
- Compare Loan Estimates and total costs rather than choosing a lender from a brand narrative or advertised rate.
Conclusion
Valon is a useful case study in how mortgage technology can become a mortgage business—and then separate again. The company did not begin by chasing consumer loan volume. It built servicing software, operated a real servicer to prove the system under regulation, added lending, and eventually sold the mortgage operating business to Carrington while keeping the technology platform.
That history is more informative than a simple star-rating review because it explains both Valon’s strengths and its risks. The platform was shaped by real servicing operations, but servicing itself is where borrowers feel every mistake in payment posting, escrow, insurance, transfers, and support.
For a borrower, the decision remains concrete: compare the Loan Estimate, verify the current legal entity and state eligibility, ask who will service the loan, keep transfer records, and monitor escrow. The best mortgage is not the one with the most interesting technology story. It is the one whose costs, execution, and post-closing service fit the borrower’s actual situation.
Frequently Asked Questions
Is Valon Mortgage legit?
Valon operated as a licensed mortgage lender and servicer, and its mortgage operating business was acquired by Carrington Mortgage Services in 2026. Legitimacy does not mean every customer has a good experience; borrowers should still verify licensing, documents, and the current servicer.
Who owns Valon Mortgage now?
Carrington Mortgage Services completed its acquisition of Valon Mortgage in August 2026. Valon Technologies remains a separate technology company focused on ValonOS.
Does Valon Mortgage refinance loans?
Valon’s borrower-facing help center has listed standard refinances and cash-out options among its mortgage products. Current availability should be confirmed with the operating lender because ownership and product offerings can change.
Does Valon offer HELOCs?
Valon’s help center lists HELOCs and home equity loans in selected states. Home-equity availability is narrower than standard mortgage availability, so borrowers should check the current state list before applying.
Does Valon offer FHA, VA, or USDA loans?
Valon’s help center states that it offers FHA loans but does not currently support VA or USDA loans.
Who services Valon loans?
Historically, Valon said it serviced most loans it originated but could transfer some loans because of financing-partner constraints. After Carrington’s 2026 acquisition, borrowers should rely on their current servicing notice and official statement rather than older assumptions.
Does Valon Mortgage operate in New York?
Valon’s help center lists New York among the states where standard residential mortgages were not offered. Product and licensing coverage can change, so verify current eligibility before applying.
Methodology
Research was conducted on October 4, 2026. A current high-visibility search sample for “Valon Mortgage,” “Valon Mortgage review,” “Valon Mortgage complaints,” “Valon Mortgage loans,” and servicing-related variants was reviewed before drafting. The sample included Valon’s official help center and corporate pages, HousingWire coverage of the Carrington transaction, ConsumerAffairs, Trustpilot, Better Business Bureau review and complaint pages, Birdeye/Google review aggregation, MortgageTechReview, Newrez/Rithm partnership material, and current ValonOS product information. Search rankings vary by location, personalization, device, and index freshness, so this is a competitive research sample rather than a permanent global ranking claim.
The dominant pages were strongest on customer reviews, product lists, state availability, and company descriptions. Their biggest shared weakness was timing: many pages still describe Valon primarily as a standalone fintech lender or servicer and do not fully center the 2026 Carrington acquisition. This article therefore uses the servicing-first-to-technology-platform transition as its structural angle rather than copying a standard lender-review template.
Primary validation was prioritized for products, state availability, servicing policy, and corporate status. Public review sites were used only to identify recurring experience themes; individual complaints were not treated as verified facts about the average customer.
Limitations: mortgage products, state licensing, rates, and servicing arrangements can change after publication. Company-reported efficiency and satisfaction metrics for ValonOS have not been treated as independently audited performance measures. Readers should verify current loan terms and servicing instructions directly before acting.
This article was drafted with AI assistance and reviewed by a human editor before publishing. All data, citations, and claims have been independently verified against primary sources.
References
- Carrington Mortgage Services. (2026). Carrington and Valon form strategic partnership to power the next generation of government servicing.
- HousingWire. (2026, August 4). Carrington completes acquisition of Valon Mortgage.
- Newrez. (2026, February 2). Rithm Capital deepens partnership with Valon; AI-native platform to advance Newrez servicing capabilities.
- Valon. (2026). About us: Modern mortgage servicing technology.
- Valon Mortgage Help Center. (2025). What types of home loans does Valon Mortgage offer?
- Valon Mortgage Help Center. (2025). Does Valon Mortgage offer home loans in my state?
- Valon Mortgage Help Center. (2025). Will Valon Mortgage service my home loan?
- Better Business Bureau. (2026). Valon Mortgage Inc customer reviews and complaints.
- ConsumerAffairs. (2026). Valon Mortgage reviews.
- Trustpilot. (2026). Valon Mortgage reviews.

An Amortization Schedule shows exactly how each loan payment is split between interest and principal, but the most important fact is often hidden in plain sight: on a $300,000, 30-year fixed loan at 6.5%, the first scheduled payment of about $1,896.20 sends roughly $1,625.00 to interest and only $271.20 to principal. The table is therefore not just bookkeeping. It is a map of when debt actually shrinks, how expensive time is, and whether a repayment strategy is doing what the borrower thinks it is doing.
Most high-ranking explainers cover the standard mechanics well. They define principal and interest, provide a calculator, and show that interest is heavier at the beginning. The gaps appear when the loan stops being standard. Payment-option adjustable-rate mortgages can add unpaid interest to principal. Balloon structures can leave a large balance due before a long “amortization period” is finished. Recasting can lower the required payment without replacing the existing loan. Tax amortization of acquired business intangibles is a separate concept again, despite sharing the same word.
This guide treats the schedule as a decision instrument rather than a static chart. It starts with the math, then tests the assumptions behind that math, shows how extra payments change the curve, explains what a recast resets and what it does not, and separates consumer-loan amortization from tax amortization. The examples are educational and use a fixed-rate monthly model; actual lender calculations can differ because of payment timing, day-count conventions, fees, escrow, and contract terms.
What the Schedule Actually Measures
For a fully amortizing fixed-rate loan, the scheduled payment is designed to bring the balance to zero by the final payment. Each period follows the same basic sequence: interest is calculated on the outstanding balance, the payment covers that interest, and the remainder reduces principal. Because the balance is largest at the beginning, the interest share is largest there too.
For a monthly loan with principal P, monthly rate r, and n scheduled payments, the fixed payment is calculated as: Payment = P × r(1+r)^n ÷ [(1+r)^n − 1]. That formula is useful, but the schedule becomes more useful when the borrower reads the columns as a chain: beginning balance → interest charge → principal reduction → ending balance.
The table below uses a $300,000 loan, 6.5% annual rate, and 30-year term. It excludes taxes, insurance, fees, and escrow so the amortization mechanics remain visible.
| Payment | Scheduled payment | Interest | Principal | Balance after payment |
| 1 | $1,896.20 | $1,625.00 | $271.20 | $299,728.80 |
| 12 | $1,896.20 | $1,608.40 | $287.81 | $296,646.82 |
| 60 | $1,896.20 | $1,523.20 | $373.01 | $280,832.93 |
| 120 | $1,896.20 | $1,380.41 | $515.80 | $254,328.38 |
| 180 | $1,896.20 | $1,182.95 | $713.25 | $217,677.42 |
| 233 | $1,896.20 | $946.50 | $949.70 | $173,789.36 |
| 240 | $1,896.20 | $909.90 | $986.30 | $166,995.85 |
| 300 | $1,896.20 | $532.33 | $1,363.87 | $96,912.49 |
| 360 | $1,896.20 | $10.22 | $1,885.99 | $0.00 |
The crossover point in this example is payment 233: principal finally exceeds interest in the scheduled payment. That is not a universal month; it moves with the rate and term. The practical lesson is broader. A lower monthly payment can hide a much slower equity-building path when the term is long.
The Assumptions Hidden Behind a “Normal” Table
A clean amortization table can create false confidence if the contract does not match the model. Before trusting any calculator, check four inputs: whether the rate can change, whether every required payment covers all accrued interest, whether the maturity date matches the amortization period, and whether fees or escrow are being mixed into the displayed payment.
| Loan structure | What happens to the schedule | Main risk to watch |
| Fixed-rate, fully amortizing | Payment is normally stable; principal share rises as balance falls | Taxes, insurance, fees, and prepayment rules may sit outside the table |
| Adjustable-rate mortgage | Schedule can be recalculated when the rate changes | Future payment and total interest are not fixed |
| Interest-only period | Principal may not fall during the interest-only phase | Payment can jump when principal amortization begins |
| Negative amortization | Payment is less than accrued interest, so unpaid interest is added to balance | Debt grows even while payments are being made |
| Partially amortizing / balloon | Payments are based on a longer amortization horizon than the actual maturity | Large lump-sum balance remains due at maturity |
The Consumer Financial Protection Bureau explains the negative-amortization mechanism clearly for payment-option ARMs: a minimum payment can be too small to cover interest, and the unpaid interest is then added to principal. A schedule that assumes the balance always falls would be wrong for that payment choice.
Negative Amortization: When Paying Does Not Mean Owing Less
Negative amortization reverses the usual intuition. Suppose a loan accrues $1,000 of interest for a month but permits a $700 minimum payment. The unpaid $300 does not disappear. If the contract capitalizes it, the balance rises by $300 before the next interest calculation. Repeating that process increases the base on which future interest is calculated.
The danger is not merely a larger balance. Payment-option loans can later recast or reset, forcing the required payment to reflect the higher balance over the remaining term. The exact trigger and size of any payment change depend on the contract, so universal claims such as “payments jump 30% to 50%” should not be treated as a rule. The schedule should be rebuilt using the actual recast terms rather than a generic fixed-rate template.
Extra Payments: The Math Matters More Than the Label
In the $300,000 example, scheduled interest over 30 years is about $382,633. If the borrower adds $158.02 to principal every month—the annual equivalent of one additional scheduled monthly payment—the model pays off in 290 months instead of 360 and reduces total modeled interest by about $87,256. This is a useful illustration, not a lender quote: the result assumes every extra dollar is applied immediately to principal and no prepayment charge applies.
Biweekly plans need even more care. “Pay half the monthly payment every two weeks” produces 26 half-payments, equal to 13 full monthly-payment equivalents each year. But another formula sometimes called biweekly simply divides 12 monthly payments across 26 dates; that does not create an extra annual payment. Terminology is inconsistent, so the cash-flow definition matters more than the marketing label.
Servicing practice matters too. A lender may not apply a half-payment to principal on the day it arrives; some systems hold partial payments until enough money is available for a full contractual payment. That means a simple 26-period calculator can differ from the loan’s actual accounting. Before enrolling in a third-party biweekly service, ask the servicer how partial payments are posted and whether the same result can be achieved by making principal-only additions directly.
| Repayment approach | Annual scheduled-payment equivalents | What changes | What to verify |
| Monthly only | 12 | Baseline amortization | Contract rate, term, fees |
| Half-payment every two weeks | 13 | Usually adds one monthly-payment equivalent per year | When partial payments are posted and how extra is applied |
| Monthly + 1/12 extra principal | 13 | Spreads one extra payment across the year | Principal-only designation and prepayment terms |
| Random lump-sum principal | Varies | Reduces balance immediately if correctly applied | Whether required payment changes automatically—it usually does not without recast |
Recasting Resets the Payment, Not the Interest Rate
A large principal payment and a mortgage recast are related but not identical. A borrower can make a lump-sum principal payment and continue making the old scheduled payment, which generally accelerates payoff. A recast asks the servicer to re-amortize the lower balance across the remaining term, lowering the required principal-and-interest payment instead.
Current lender guidance illustrates the distinction. Chase describes mortgage recasting as spreading the remaining balance over the remaining term while keeping the current interest rate; it also notes that its recast process does not require a new credit check or appraisal. Eligibility and procedures vary by servicer and loan type, so borrowers should request the exact requirements before sending a large payment.
Refinancing is structurally different because the old loan is replaced with a new one. That can change the rate, term, loan type, and lender, but it also introduces new underwriting and closing costs. A recast is therefore mainly a cash-flow decision: use a lump sum to reduce the balance, then trade some of the potential payoff acceleration for a lower required payment.
Use the Table as a Behavioral Tool, Not Just a Statement
An amortization table can improve decisions because it makes invisible trade-offs visible. Three checkpoints are especially useful: the first-year principal reduction, the principal-interest crossover point, and the balance on the date a borrower expects to move, refinance, retire, or sell the asset. Those dates turn an abstract 30-year promise into numbers attached to real decisions.
The same principle appears in broader behavior-change systems: evidence is more useful when it changes the next action. For debt, that means using the schedule to set a specific extra-principal rule, identify a liquidity floor that should not be sacrificed to prepayment, and define the date when the plan will be reviewed.
Extra principal also competes with other uses of cash. Aperplexity’s guide to investment strategies separates risk, time horizon, liquidity, costs, and taxes rather than treating every spare dollar as interchangeable. Paying down a guaranteed loan cost can be attractive, but the borrower still needs emergency liquidity and should compare the after-tax cost of debt with alternative uses of cash.
Business Loans and Tax Amortization Are Different Problems
For a business term loan, the loan amortization schedule is primarily a cash-flow and accounting tool. It separates the cash payment into principal and interest, helping a business forecast debt service and record the liability reduction correctly. A loan with an interest-only period followed by amortization needs a two-stage model rather than a single fixed-payment formula.
That distinction is especially useful in startup modeling. The Startup Booted guide discusses financial models as decision systems that connect revenue assumptions, operating costs, hiring, cash, and financing needs. Debt service belongs in that system because principal consumes cash even though it is not itself an operating expense.
Tax treatment adds another layer. For U.S. individual homeowners, mortgage interest is not automatically deductible merely because it appears in an amortization table. Eligibility depends on current tax rules, the use of loan proceeds, debt limits, itemizing, and other requirements. Principal repayment is not a mortgage-interest deduction.
The IRS Publication 936 is the primary reference for U.S. home-mortgage interest rules. Separately, the IRS requires many acquired Section 197 intangibles—including goodwill, certain customer-based intangibles, franchises, trademarks, and trade names—to be amortized over 15 years for tax purposes. This is asset-cost amortization, not loan repayment.
For the business-asset rules, see the IRS instructions for Form 4562. The key editorial point is to keep three ideas separate: loan principal amortization, deductible interest where applicable, and tax amortization of qualifying intangible assets. They share terminology but answer different accounting and tax questions.
The Schedule Should Follow the Decision Date
A 30-year schedule does not mean every borrower should optimize for year 30. Someone expecting to sell a home in seven years should care about the balance after 84 payments, not just lifetime interest. A business expecting a refinancing event in year three should stress-test the remaining balance and refinance risk at that point. A balloon borrower should treat maturity as the hard deadline, even if the payment was calculated using a longer amortization horizon.
This “decision-date” framing is the same reason an all-in housing budget matters before signing a lease. Aperplexity’s apartment-renting guide separates sticker rent from the true cash requirement. Loan analysis needs the same discipline: the scheduled principal-and-interest payment is not the whole housing cost, and the lifetime total is not the only time horizon that matters.
How to Build an Amortization Schedule in Excel or Google Sheets
A basic fixed-rate schedule needs inputs for original principal, annual rate, term, payment frequency, and any extra principal. The following structure is easier to audit than a single opaque formula because each row exposes the balance transition.
- Monthly rate: annual interest rate ÷ 12.
- Number of payments: years × 12.
- Scheduled payment: use PMT(monthly_rate, number_of_payments, -principal).
- Interest for each row: beginning_balance × monthly_rate.
- Scheduled principal: scheduled_payment − interest.
- Total principal paid: scheduled_principal + extra_principal, capped so the balance never goes below zero.
- Ending balance: beginning_balance − total_principal_paid.
- Next row beginning balance: prior row ending balance.
For a business loan with an interest-only phase, do not force the PMT formula across the entire term. During the interest-only rows, payment normally covers the period’s interest under the contract. At the amortization start date, calculate a new payment using the remaining principal, current contractual rate, and remaining amortizing periods. For a variable-rate loan, rebuild the forward schedule whenever the rate changes according to the contract.
The Future of Amortization Schedules in 2027
The useful direction for 2027 is not a new amortization formula; the core math is mature. The change is how schedules are used. Major lender and calculator sites already let borrowers test extra payments, payoff dates, and recast scenarios interactively. The likely next step is tighter integration between servicing portals, transaction data, and scenario tools so a borrower can compare “keep payment,” “add principal,” “recast,” and “refinance” using the actual current balance rather than re-entering estimates.
That convenience does not remove model risk. Variable-rate debt, interest-only periods, payment options, irregular extra payments, fees, and lender posting rules still require contract-specific logic. A more sophisticated interface can make a wrong assumption look more authoritative, so the strongest tools will need to expose their assumptions instead of hiding them.
For businesses, the same trend points toward integrated cash-flow models in which the debt schedule updates alongside hiring, revenue, taxes, and financing scenarios. That is more useful than a standalone table because the real question is rarely “what is the next principal payment?” It is “what does this debt structure do to liquidity at the moment another decision has to be made?”
Key Takeaways
- A schedule is trustworthy only when its rate, payment timing, term, and loan structure match the actual contract.
- On the illustrative 30-year loan, the principal-interest crossover occurs at month 233, showing how slowly principal can fall early in a long term.
- Negative amortization is the critical exception to the “every payment reduces debt” intuition: unpaid interest can increase principal.
- One extra annual payment can materially change payoff time, but “biweekly” programs must be defined by cash flow and servicer posting rules.
- A lump-sum principal payment accelerates payoff if the old payment continues; recasting instead recalculates a lower required payment over the remaining term.
- Home-mortgage interest rules and Section 197 tax amortization are separate from the loan’s principal schedule.
- The best schedule is built around the borrower’s real decision date—sale, refinance, maturity, retirement, or a business cash-flow milestone—not only the final payment.
Conclusion
An amortization schedule is most useful when it is treated as a model with assumptions, not as a decorative table attached to a loan. For a standard fixed-rate loan, it explains why interest dominates early, when principal begins to accelerate, and how extra payments alter the path. For nonstandard debt, it becomes a diagnostic tool: does the payment cover all interest, can the balance grow, is there a balloon at maturity, and will the payment be recalculated later?
The practical discipline is simple. Match the schedule to the contract. Separate principal, interest, escrow, and fees. Model extra payments only after confirming how the servicer applies them. Use recasting for a lower required payment only when that objective is more important than keeping the higher payment and shortening payoff. And for tax questions, move from the payment table to the actual tax rules rather than assuming every interest line is deductible. The arithmetic is straightforward; the value comes from asking whether the arithmetic represents the real loan.
Frequently Asked Questions
What is an amortization schedule in simple terms?
It is a payment-by-payment table showing the amount paid, the interest charged, the principal repaid, and the remaining loan balance. On a fully amortizing fixed-rate loan, the interest share usually falls over time while the principal share rises.
How do you read an amortization table principal vs. interest?
Start with the beginning balance, then check the interest charge for that period. Subtract the interest from the scheduled payment to find the principal reduction. The ending balance should equal the beginning balance minus principal paid, subject to any extra principal or contract-specific adjustments.
Does an extra payment automatically lower my monthly payment?
Usually not on a standard fixed-rate mortgage. Extra principal lowers the balance and can shorten payoff if the required payment stays unchanged. To lower the required payment on an eligible mortgage, the borrower may need to request a recast from the servicer.
Is a biweekly amortization schedule always better than monthly payments?
No. The benefit depends on what “biweekly” means and how the servicer posts partial payments. Twenty-six half-payments equal 13 monthly-payment equivalents per year, but a plan that merely redistributes 12 payments across 26 dates does not create the same extra principal.
What is a negative amortization schedule example?
If a loan accrues $1,000 of interest for a month but permits a $700 payment, the unpaid $300 can be added to principal under a negative-amortization structure. The next period can then charge interest on the larger balance.
What is the difference between recasting and refinancing?
Recasting keeps the existing loan and generally recalculates the required payment after a principal reduction using the same rate and remaining term. Refinancing replaces the existing loan with a new one and can change the rate, term, loan type, and lender.
Is interest on an amortization schedule tax deductible?
Not automatically. U.S. mortgage-interest deductions depend on current tax rules, the use and amount of the debt, itemizing, and other requirements. Business-loan interest and tax amortization of intangible assets follow different rules. Consult the applicable IRS guidance or a qualified tax professional for a specific situation.
Methodology
Research was conducted on October 1, 2026. Before drafting, I reviewed a current high-visibility sample for the exact query and close-intent variants, including WSJ Buy Side, Rocket Mortgage’s mortgage-amortization explainer and calculator, Calculator.net’s amortization and mortgage-amortization calculators, Corporate Finance Institute, AccountingTools, CalcCottage, Chase’s mortgage-recast guidance, and Microsoft Excel discussions/templates. Search order varies by location, device, personalization, and index freshness, so this is a competitive SERP sample rather than a permanent global ranking claim.
The recurring strengths were clear definitions, fixed-rate examples, payment calculators, and explanations of principal versus interest. The main gaps were contract-assumption checks, negative amortization, balloon structures, the posting mechanics behind biweekly plans, the difference between a principal curtailment and a recast, and the boundary between loan amortization and tax amortization. The article structure was built around those gaps rather than copying any competitor’s heading sequence.
Primary validation used the Consumer Financial Protection Bureau for payment-option ARM behavior and the Internal Revenue Service for home-mortgage interest and Section 197 intangible-amortization rules. Chase and current mortgage-industry explainers were used as practical examples of recast mechanics, with the article explicitly noting that lender policies vary. Calculations were independently reproduced using the standard fixed-payment formula and a month-by-month balance model.
References
- Consumer Financial Protection Bureau. (2024, February 2). What is an option or payment-option ARM?
- Internal Revenue Service. (2025). Publication 936: Home mortgage interest deduction.
- Internal Revenue Service. (2026). Instructions for Form 4562 (2025): Depreciation and amortization.
- Internal Revenue Service. (n.d.). Intangibles. Retrieved October 1, 2026.
- Chase. (2025, September 30). What is a mortgage recast?
- Rocket Mortgage. (2026, March 16). What is a mortgage amortization schedule?
- Rocket Mortgage. (2026, August 28). Mortgage recasting: What to know before you reamortize.
-
 Technology1 month ago
Hitomi la in 2026: Domain Status, Safety and Risks
-

 Technology1 month ago
ThomsonKids.com: Website Guide, Topics & Trust Check
-

 General1 month ago
Voozon.com: What It Is and How the Platform Works
-

 Business1 month ago
incabizgrowth.com Review: Content, Trust & Use
-

 Technology1 month ago
thesindi com Review: What TheSindi.com Really Offers
-

 Technology2 weeks ago
Scrolller in 2026: How It Works, Risks and Alternatives
-

 Business1 month ago
5starsstocks.com Review: Features, Trust and Safety
-
 Technology3 weeks ago
Web Development Best Practices: A 2026 Quality System